What Is a Title Company and What Do They Do in Real Estate?
Title companies are key players in nearly every real estate transaction. Whether you are on the buying or selling side of the table, you will almost certainly work with one, yet many people go through the entire closing process without really understanding the title company's role. In simple terms, a title company is a neutral third party tasked with verifying ownership, managing important documents, and making sure that closing goes smoothly for both the buyer and seller. However, their involvement goes much deeper than just administrative work, as you'll see.
Table of Contents
- What Is a Title Company and What Do They Do in Real Estate?
- What Is a Title Company?
- What Does a Title Company Do?
- Why Title Companies Are Important in Real Estate Transactions
- What's the Difference Between a Title Company, a Real Estate Agent, and an Attorney?
- Who Chooses the Title Company?
- How Much Does a Title Company Cost?
- How Title Companies Work with Title Search Reports
- Frequently Asked Questions About Title Companies
What Is a Title Company?
A real estate title company is a business that operates in three core areas: researching property ownership history, issuing title insurance, and managing the closing process. Their primary role is making sure that a property is legally and safely transferred from one owner to another.
Think of title companies as the referees of real estate transactions. They do not represent the buyer or the seller. Instead, they act as neutral third parties that ensure the deal is legally sound, properly documented, and free of hidden ownership problems. Because of this role, buyers, sellers, and lenders all rely on title companies to reduce risk and prevent the types of mistakes that can lead to legal disputes, financial losses, or a failed closing.
What Does a Title Company Do?
Title companies generally handle four key aspects of real estate transactions:
Conducting a Title Search
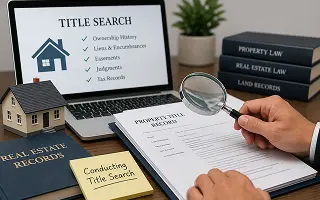
The first major task a title company handles is performing a title search. This is a thorough review of public records (deeds, mortgages, court judgments, tax records, etc.) to trace the property's ownership history, often going back 30 to 60 years or more. The purpose of the title search is to confirm that the person selling has the legal authority to do so, and to also identify any issues that could affect the sale. This often includes:
- Unpaid liens
- Ownership gaps or unclear transfer history
- Errors in public records
- Outstanding court judgments tied to the property or its owners
For example, if a previous owner failed to pay property taxes, the title search would uncover that lien so that it can be resolved before closing.
Issuing Title Insurance
Because the most thorough title search can still miss something, title companies also issue title insurance. These are insurance policies that protect against title defects or problems that were not discovered during the search. There are two types of title insurance: a lender's policy (which protects the mortgage lender) and an owner's policy (which protects the homebuyer). Both policies are issued at closing, usually as a one-time fee.
Handling the Closing Process
The title company also plays a central role in coordinating the closing (where ownership officially transfers from the seller to the buyer) and ensuring that the transaction is hitch-free. During this process, they are generally responsible for:
- Preparing and reviewing important documents
- Ensuring that all conditions of the sale have been met
- Collecting signatures from both parties
- Collecting and distributing funds (including the buyer's down payment and the seller's proceeds)
- Finalizing the transaction details
- Recording the new deed (and mortgage, where applicable) with the local government to officially document the new ownership
Managing Escrow Funds
Managing escrow funds is another important task a property title company undertakes. Escrow refers to a legal arrangement where a neutral third party holds money on behalf of the buyer and seller until all conditions of the real estate transaction are met. Throughout the home-buying process, the title company holds several types of funds in escrow. These typically include:
- The buyer's earnest money (the good-faith deposit usually provided early in the deal)
- The lender's loan funds
- Payments for taxes, insurance, and other fees (closing costs)
- Seller's proceeds
The title company does not release any money until both the buyer and seller have met their obligations. This helps to protect both parties from getting short-changed by ensuring that funds are handled securely and only distributed when everything is complete.
Why Title Companies Are Important in Real Estate Transactions
Title companies provide essential layers of protection for everyone involved in a real estate transaction. Here are a few reasons why buyers, sellers, and lenders all rely on them:
- They Prevent Costly Financial and Legal Issues: Title companies help avoid complications that could delay or cancel the sale by identifying problems early. Without a title company running a title search, you might not discover an issue (like an unpaid tax lien or a contractor's claim) until after closing, at which point you would be responsible for it. The title company ensures that such problems are uncovered and flagged on time so they can be resolved before you take ownership.
- They Ensure a Clean Transfer of Ownership: The title company verifies that the seller has the right to transfer ownership and that the buyer receives a clean title. If you are on the buyer side of the table, the title company also ensures that the deed is properly recorded with the local government (county recorder or register of deeds) so that you are officially recognized as the legal owner of the property.
- They are a Requirement for Financing: Lenders rely on title companies to reduce risk before approving and funding a mortgage. Most lenders will not release the loan funds unless a title company has done its work and assures them that the property's title is clean enough to serve as collateral.
- They Reduce Post-Closing Disputes: Even small errors like a missing signature, an incorrect legal description, or a misfiled document can lead to legal headaches years after a property is purchased. The title company's role in reviewing important transaction-related documents prevents these problems from happening in the first place, reducing the risk of future ownership conflicts.
What's the Difference Between a Title Company, a Real Estate Agent, and an Attorney?
While it's easy to confuse them, title companies, real estate agents, and real estate attorneys all play specific roles in real estate transactions:
- Title Companies: They are neutral third parties that handle property records, title searches, title insurance, escrow, and the closing process. Their focus is on verifying ownership, managing transaction details, and making sure that the overall process is legally sound.
- Real Estate Agents: They help buyers find properties and sellers list their homes. Real estate agents may represent either the buyer or seller, and they typically negotiate offers, guide their clients through the process, and coordinate with other parties (including the title company). However, they do not handle title searches or legal documents.
- Real Estate Attorneys: They provide specific legal advice and review contracts. Like agents, they may also represent any party involved in the transaction. In some states (like Georgia, New York, South Carolina, and Delaware), an attorney is legally required to oversee or handle the closing process. In other states, hiring one is optional but usually recommended, especially for complex deals. You can ask your agent or lender if you are unsure whether your state requires an attorney for closing (you should do this early in the process to avoid any scheduling delays).
Who Chooses the Title Company?
Who selects the title company for a real estate transaction generally varies depending on location and the terms of the purchase agreement. Because the buyer typically pays for the title search and insurance, they usually choose the company. However, in some areas, it is customary for the seller to choose the company if they are paying for the owner's policy. It is important to note that the Real Estate Settlement Procedures Act (RESPA) prohibits sellers from requiring buyers to use a specific title company as a condition of the sale, especially if the buyer is the one paying for the policy.
At the end of the day, the choice of title company can often be negotiated as part of the purchase agreement. While your real estate agent or lender may recommend a title company, you are not obligated to go along with their suggestion. It is always a good idea to shop around and compare quotes from at least two or three providers. Doing this can potentially save you hundreds of dollars in closing costs. If you do have a preferred company, ensure it is written into your initial offer. Bringing it up early in the process helps prevent last-minute disputes over who will manage the escrow and closing.
How Much Does a Title Company Cost?
On average, you can expect to pay the following charges for a title company's services:
-
Title Search Fee: This covers the labor of researching public records to trace the property's ownership history and identify any liens, judgments, or other “clouds” on its title.
Typical Range: $75 - $200.
-
Title Insurance Premiums: A one-time fee paid at closing for the lender's policy, owner's policy, or both.
Typical Range: 0.1% to 1% of the loan amount for the lender's policy and 0.5% to 1.0% of the property's purchase price for the owner's policy. Discounts are usually offered if you buy both policies together.
-
Closing/Settlement Fee: This covers the title company's administrative work of managing and coordinating the closing, including preparing documents, collecting signatures, distributing funds, and recording the deed.
Typical Range: $200 - $500+.
In addition to these standard charges, some title companies may charge separate fees for document preparation, notary services, wire transfers, or courier services. Keep in mind that actual fees vary by location, property value, and the specific title company. You can generally find these costs outlined in your Loan Estimate (issued within three days of your loan application, where applicable) and Closing Disclosure (issued at least three days before closing). Be sure to review both documents carefully to avoid surprises. It is also a good idea to shop around for quotes from at least two or three different companies to compare prices and get a favorable deal.
How Title Companies Work with Title Search Reports
The title search report is one of the most important documents the title company produces. A title search reviews a property's full ownership and filing history to identify any known issues. This search is initiated early in the transaction, usually right after the purchase agreement is signed and an escrow account is opened. Once the title search is completed, a report is issued listing every recorded event in the property's history (deeds, mortgages, liens, easements, court judgments, etc.). The title company reviews the results and flags any problems that need to be addressed.
Once these identified problems are cleared, the title company also issues title insurance to cover any hidden risks that the search may have missed. Together, the title search and insurance give buyers and lenders confidence that a property's ownership has been thoroughly vetted and will be transferred cleanly with minimal risks and protection for undiscovered issues.
Frequently Asked Questions About Title Companies
Is a Title Company Required When Buying a Home?
They are usually required in most cases, especially if you are financing the purchase. Lenders typically require a title company to conduct a title search, issue title insurance, and manage the closing. Even cash buyers typically use title companies to ensure they are receiving a clear title and to protect their investment.
Can You Choose Your Own Title Company?
Yes. While lenders and sellers may have preferred providers, buyers generally have the right to shop for and select their own title company. Note that local customs vary, and the choice of title company can often be negotiated as part of the initial purchase agreement.
What's the Difference Between Escrow and a Title Company?
Escrow is a service where a neutral third party holds funds until all agreed-upon conditions are met. Title companies typically provide this service as part of their role in real estate transactions, although standalone escrow companies may also do this in some states.
Do Title Companies Handle Closing?
Yes. In many cases, title companies coordinate and manage the closing process. However, in some states, a real estate attorney is required to either handle the closing themselves or work alongside the title company.
How Long Does a Title Search Take?
A typical title search takes about 2 to 10 business days. Note that actual timelines vary by property and location, with older properties, properties with complex ownership histories, and those located in counties with slow public record systems sometimes taking up to a few weeks.
What Happens If a Title Issue Is Found?
If a title issue is discovered, it is flagged by the title company and must usually be resolved by the seller before closing. This may involve paying off liens, correcting errors, or addressing ownership disputes. If the issue cannot be resolved, the closing may be delayed or canceled. In many cases, the buyer can back out of the purchase if a serious title problem cannot be fixed.
Table of Contents
- What Is a Title Company and What Do They Do in Real Estate?
- What Is a Title Company?
- What Does a Title Company Do?
- Why Title Companies Are Important in Real Estate Transactions
- What's the Difference Between a Title Company, a Real Estate Agent, and an Attorney?
- Who Chooses the Title Company?
- How Much Does a Title Company Cost?
- How Title Companies Work with Title Search Reports
- Frequently Asked Questions About Title Companies